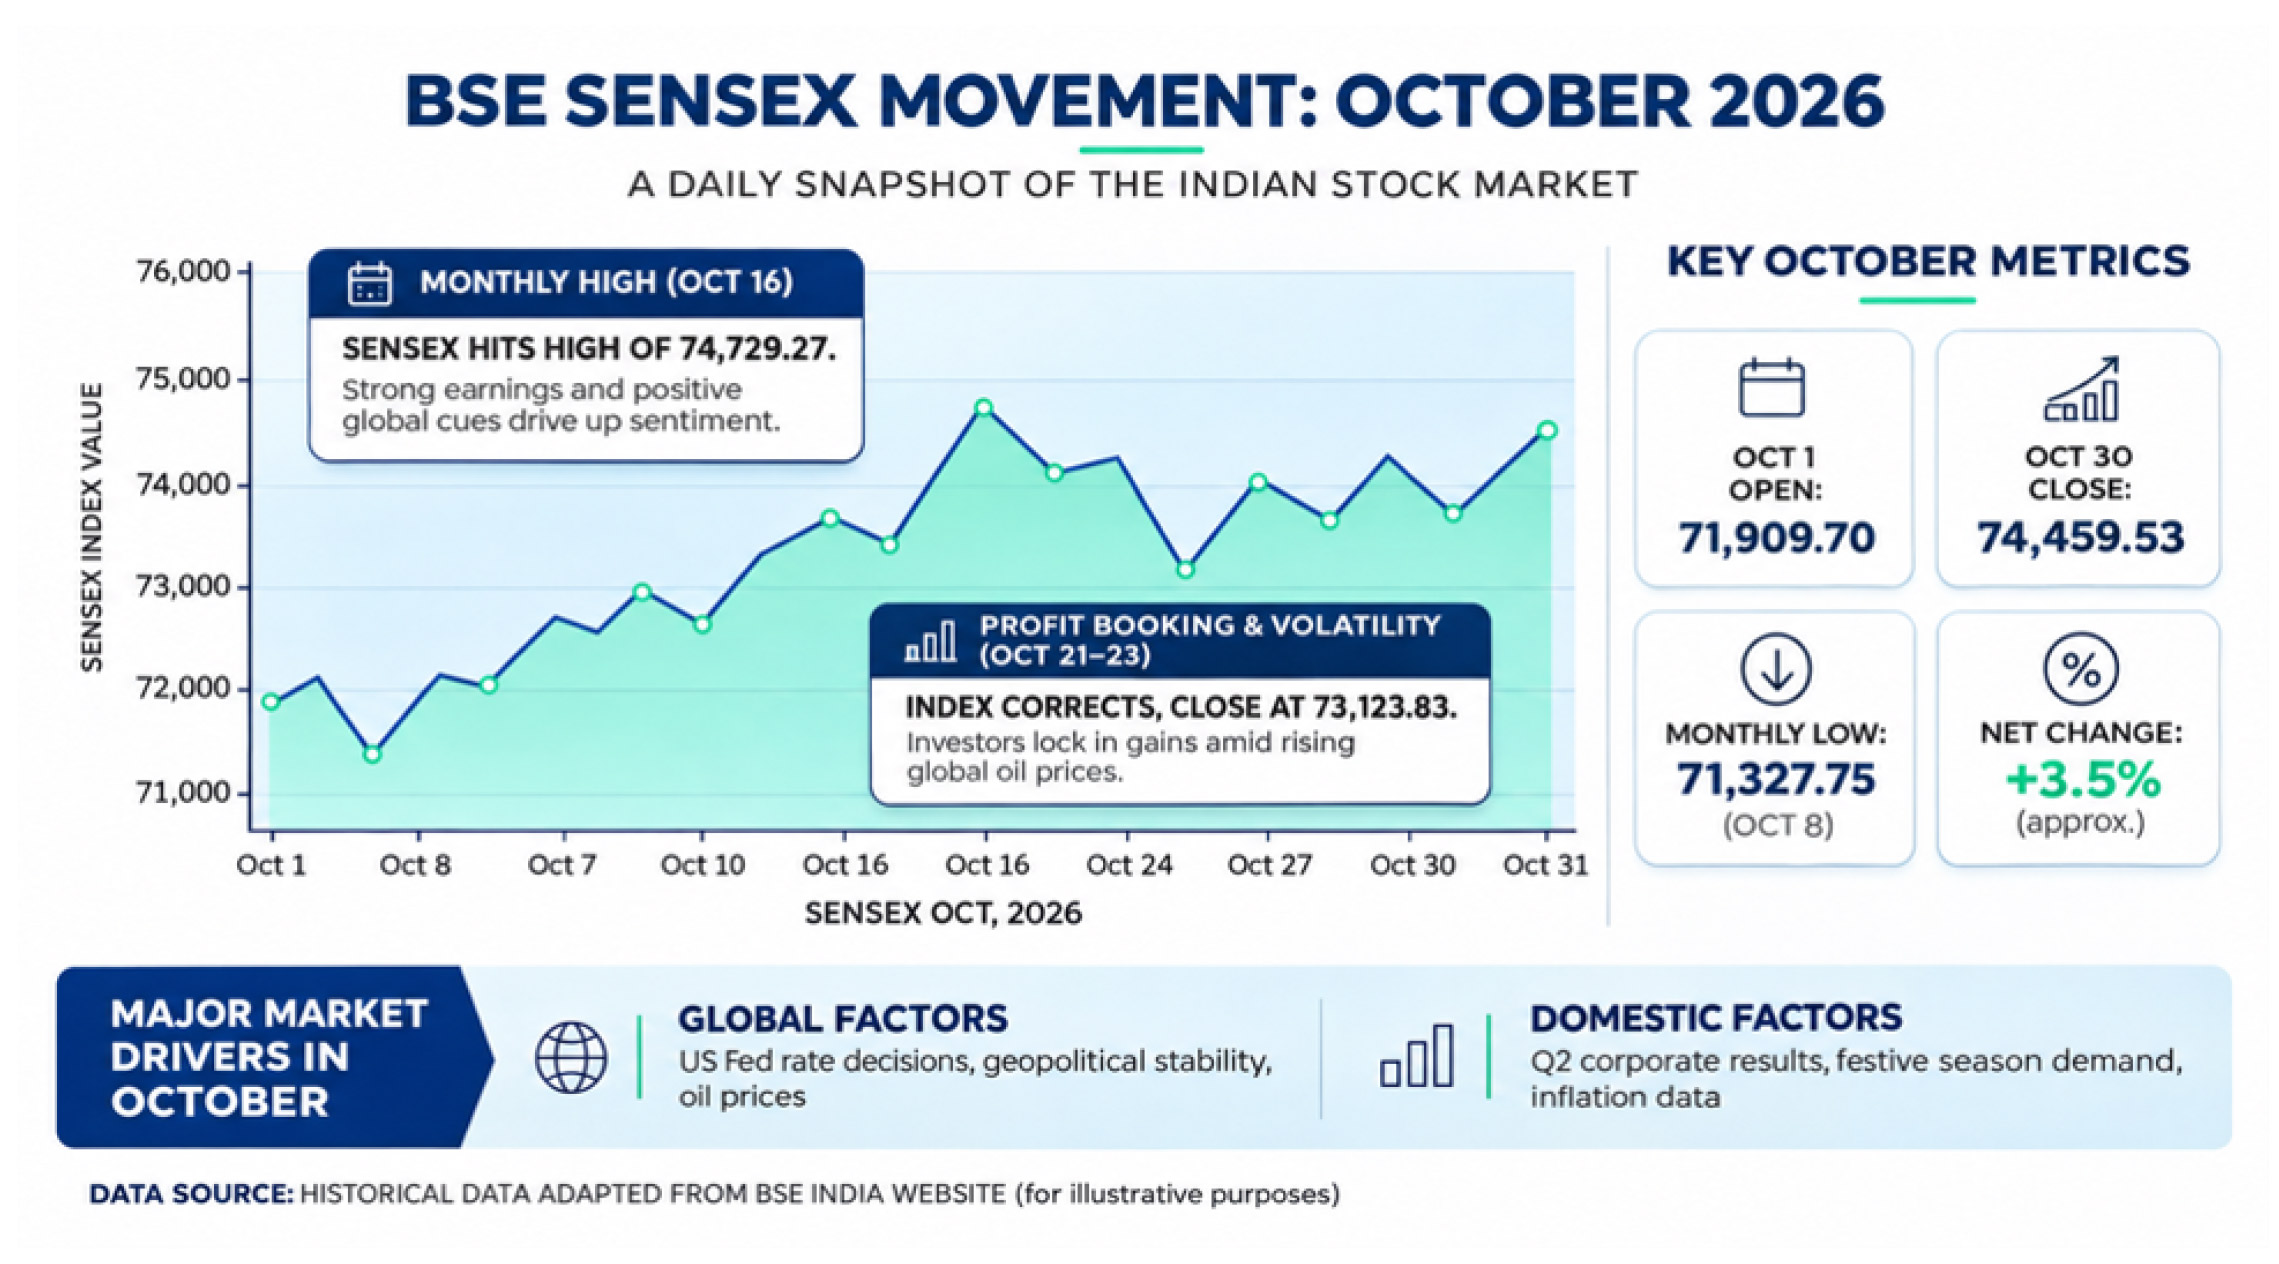
October 2026 witnessed a recovery in Indian equity markets, with the benchmark indices Sensex and Nifty reversing their two-month losing streak and ending the month in positive territory. Based on the opening levels of October 1 and closing levels of October 30, the BSE Sensex gained 3.14%, while the NSE Nifty 50 advanced 2.26%. The Sensex opened at 72,192.89 and closed at 74,459.53, registering an absolute gain of 2,266.64 points. Similarly, the Nifty opened at 22,543.70 and ended the month at 23,053.10, gaining 509.40 points.
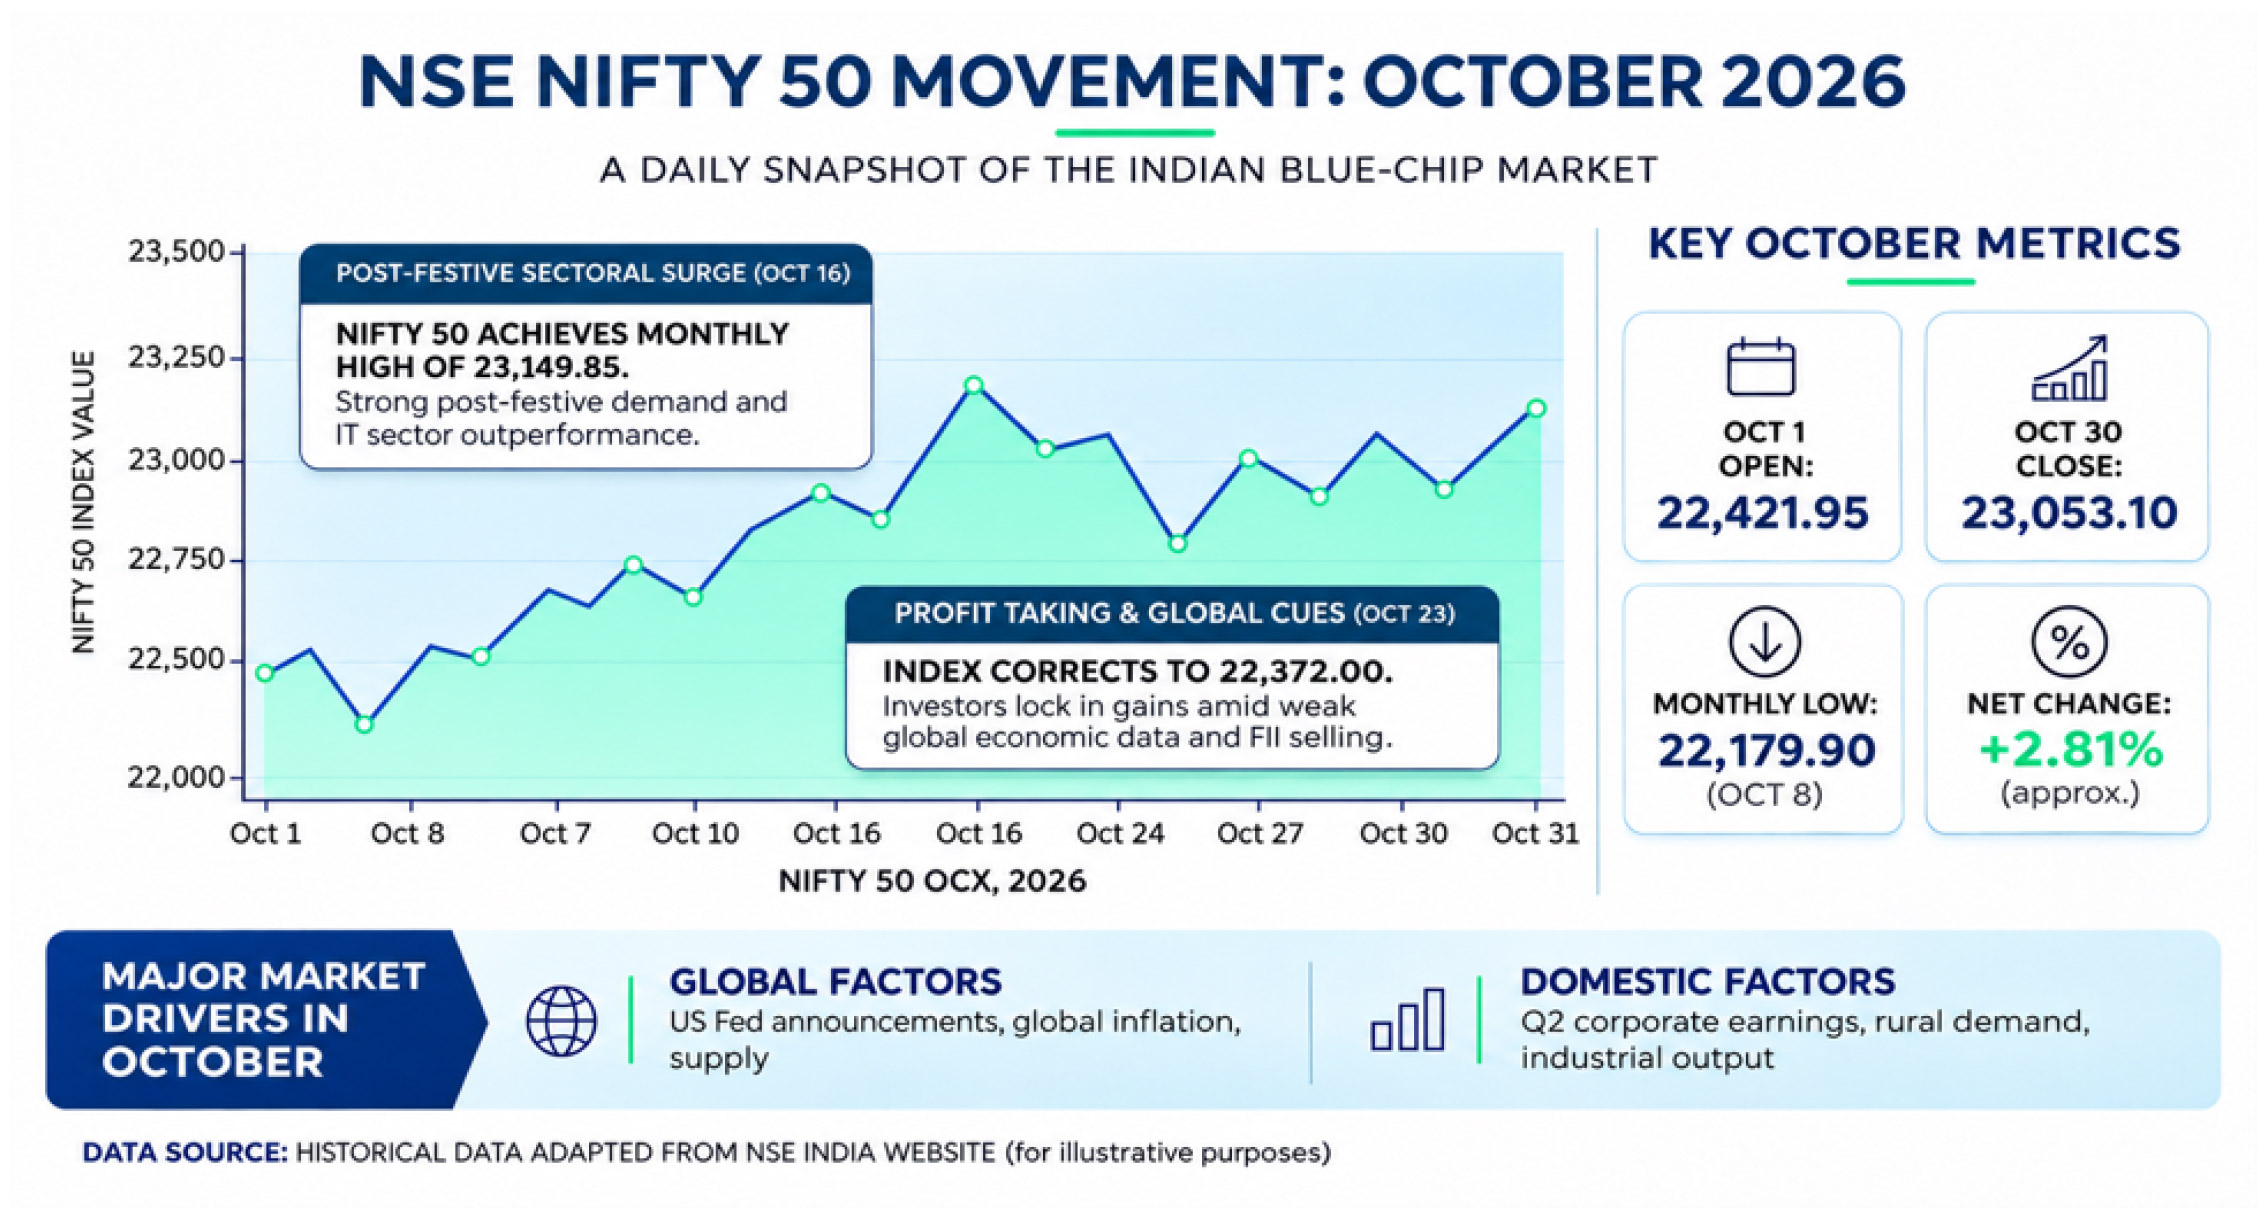
The market's performance during October was characterised by considerable volatility, with an initial phase of weakness followed by a strong recovery towards the final trading sessions. Investor sentiment remained influenced by global geopolitical developments, crude oil prices, monetary policy decisions, foreign investment flows and corporate earnings. Internationally, escalating tensions in the Middle East and concerns over disruptions to crude oil supplies kept Brent crude prices elevated, increasing worries about India's import expenditure, inflation and external balances. Higher US Treasury yields and a relatively strong US dollar also reduced the attractiveness of emerging-market equities, encouraging foreign investors to reassess their exposure to Indian markets. Weakness in global technology stocks and uncertainty surrounding international economic growth added to the cautious sentiment during the first half of the month. Foreign institutional investors (FIIs), also referred to as foreign portfolio investors (FPIs), were among the most significant factors influencing market direction during October. According to provisional exchange data, foreign institutions were net sellers of approximately ₹45,162 crore in the cash market, while domestic institutional investors (DIIs) recorded net purchases of approximately ₹62,220 crore. The scale of foreign selling was particularly significant as it marked the largest monthly FII net outflow in the available monthly comparison since June 2026. FIIs were net sellers in 14 out of 20 trading sessions, with their selling activity concentrated in the first half of the month. On October 8 alone, foreign institutions recorded net sales of approximately ₹12,944 crore, intensifying the pressure on benchmark indices. Several factors contributed to the sustained foreign investor withdrawals. Firstly, higher US Treasury yields and a stronger dollar made American financial assets relatively more attractive compared with emerging-market investments. With US 10-year government bond yields offering competitive returns, foreign investors found it more attractive to allocate capital to relatively safer US assets rather than remain exposed to the volatility of emerging markets. Secondly, elevated crude oil prices and geopolitical uncertainty increased concerns about India's macroeconomic outlook. Higher oil prices raised the risk of inflation, currency depreciation and a widening current account deficit, reducing the attractiveness of Indian equities. Thirdly, relatively expensive Indian market valuations encouraged foreign investors to explore opportunities in other Asian markets, particularly China, Hong Kong and South Korea, where valuations appeared more attractive. The artificial intelligence-led rally in North Asian technology stocks also diverted a portion of global investment flows away from India. Additionally, concerns over corporate earnings growth and the sustainability of market valuations following earlier rallies encouraged foreign investors to book profits and reduce their exposure to Indian equities.
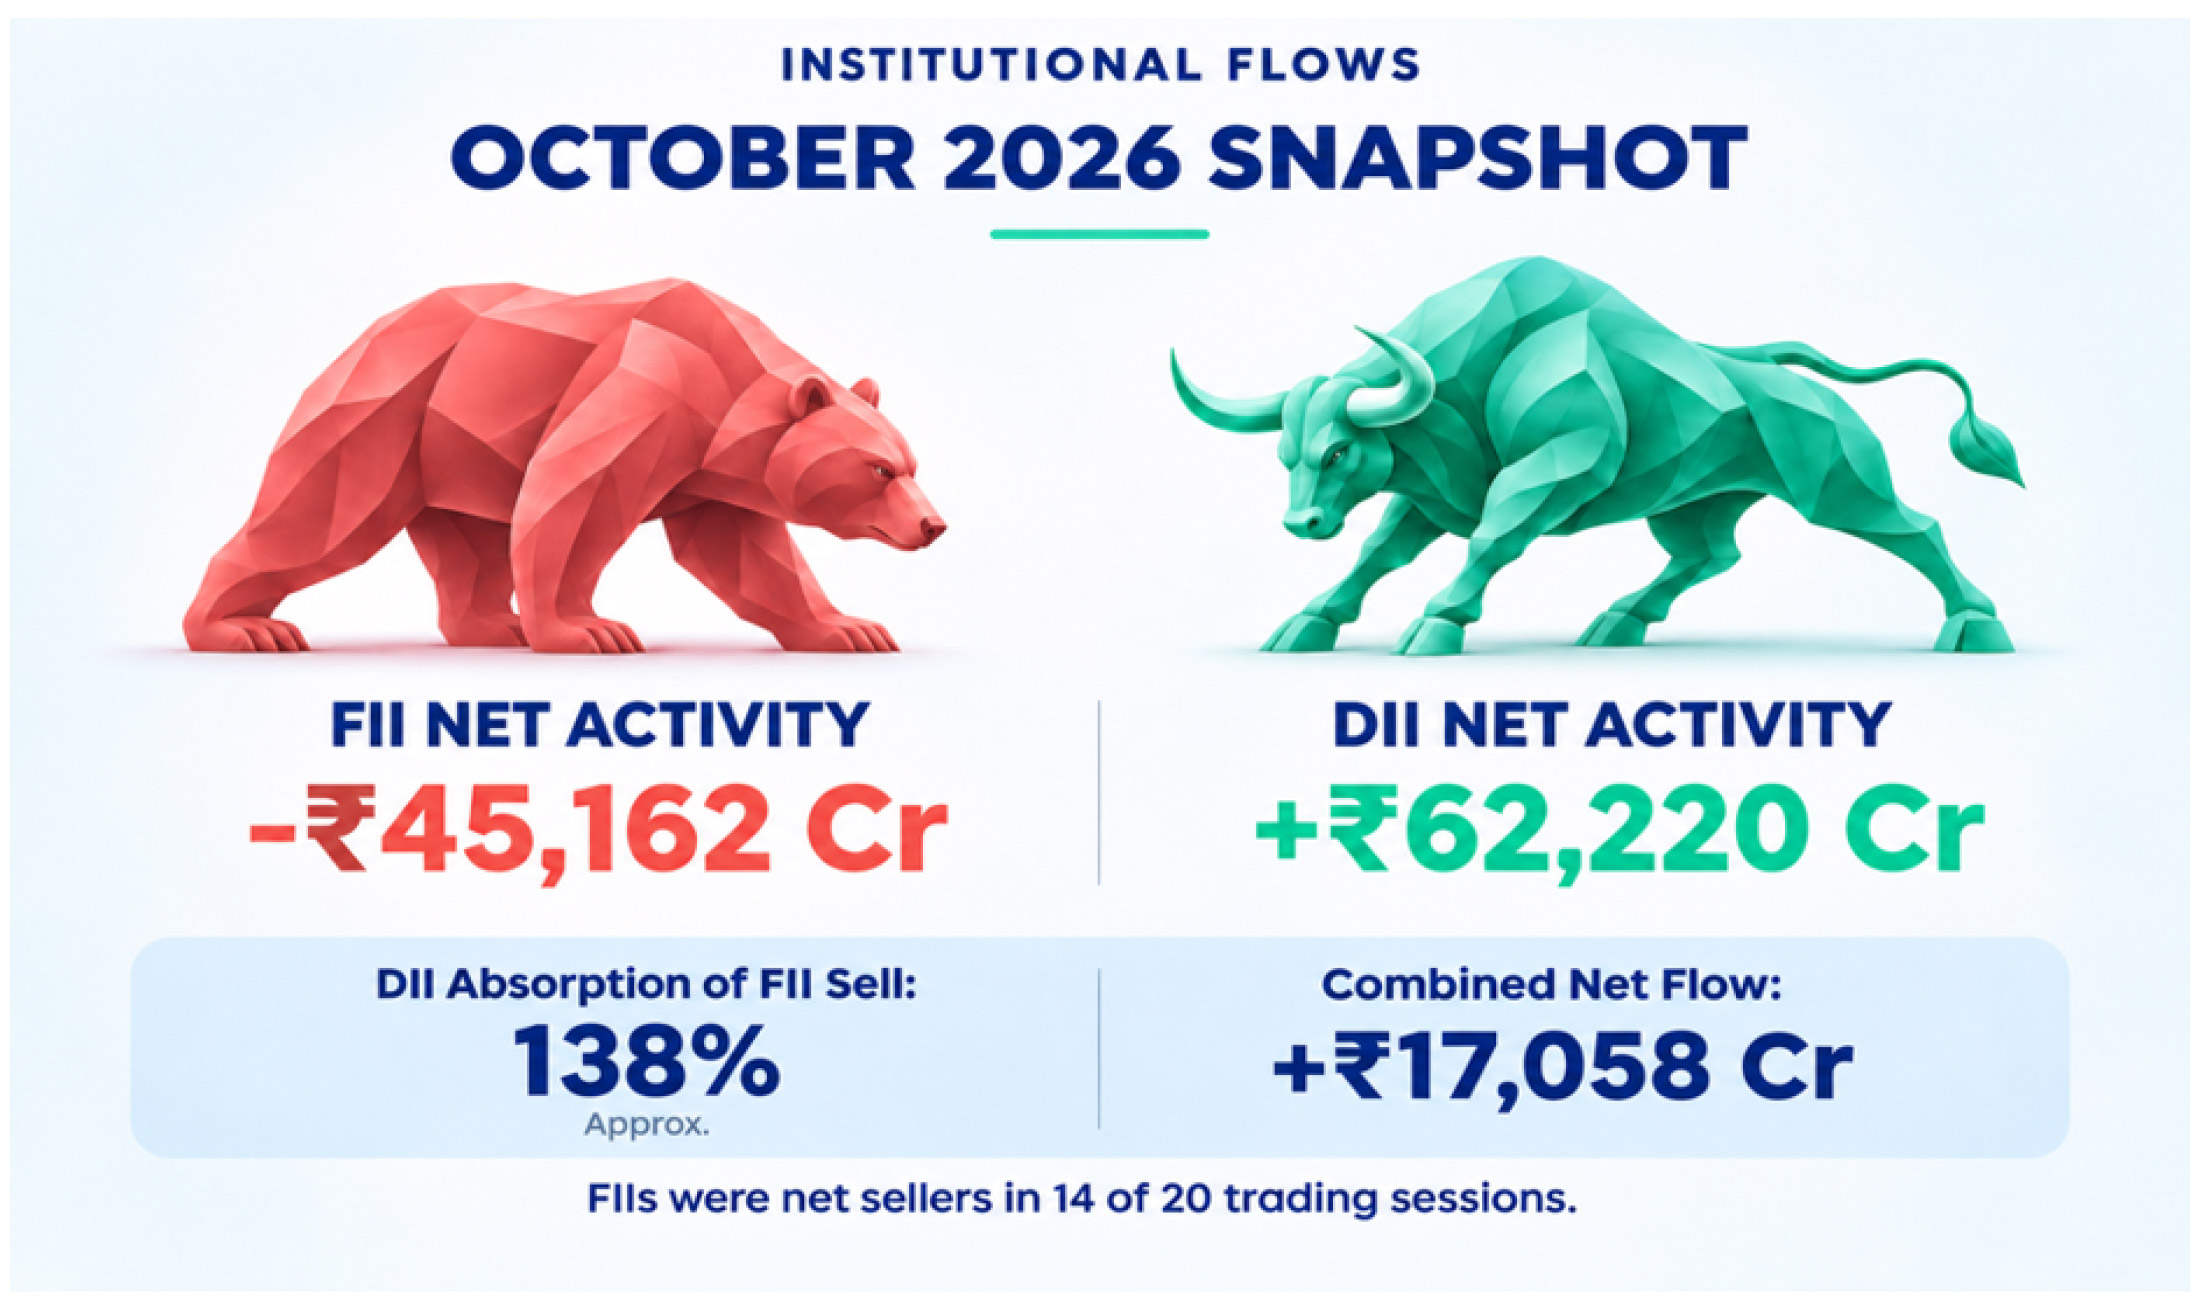
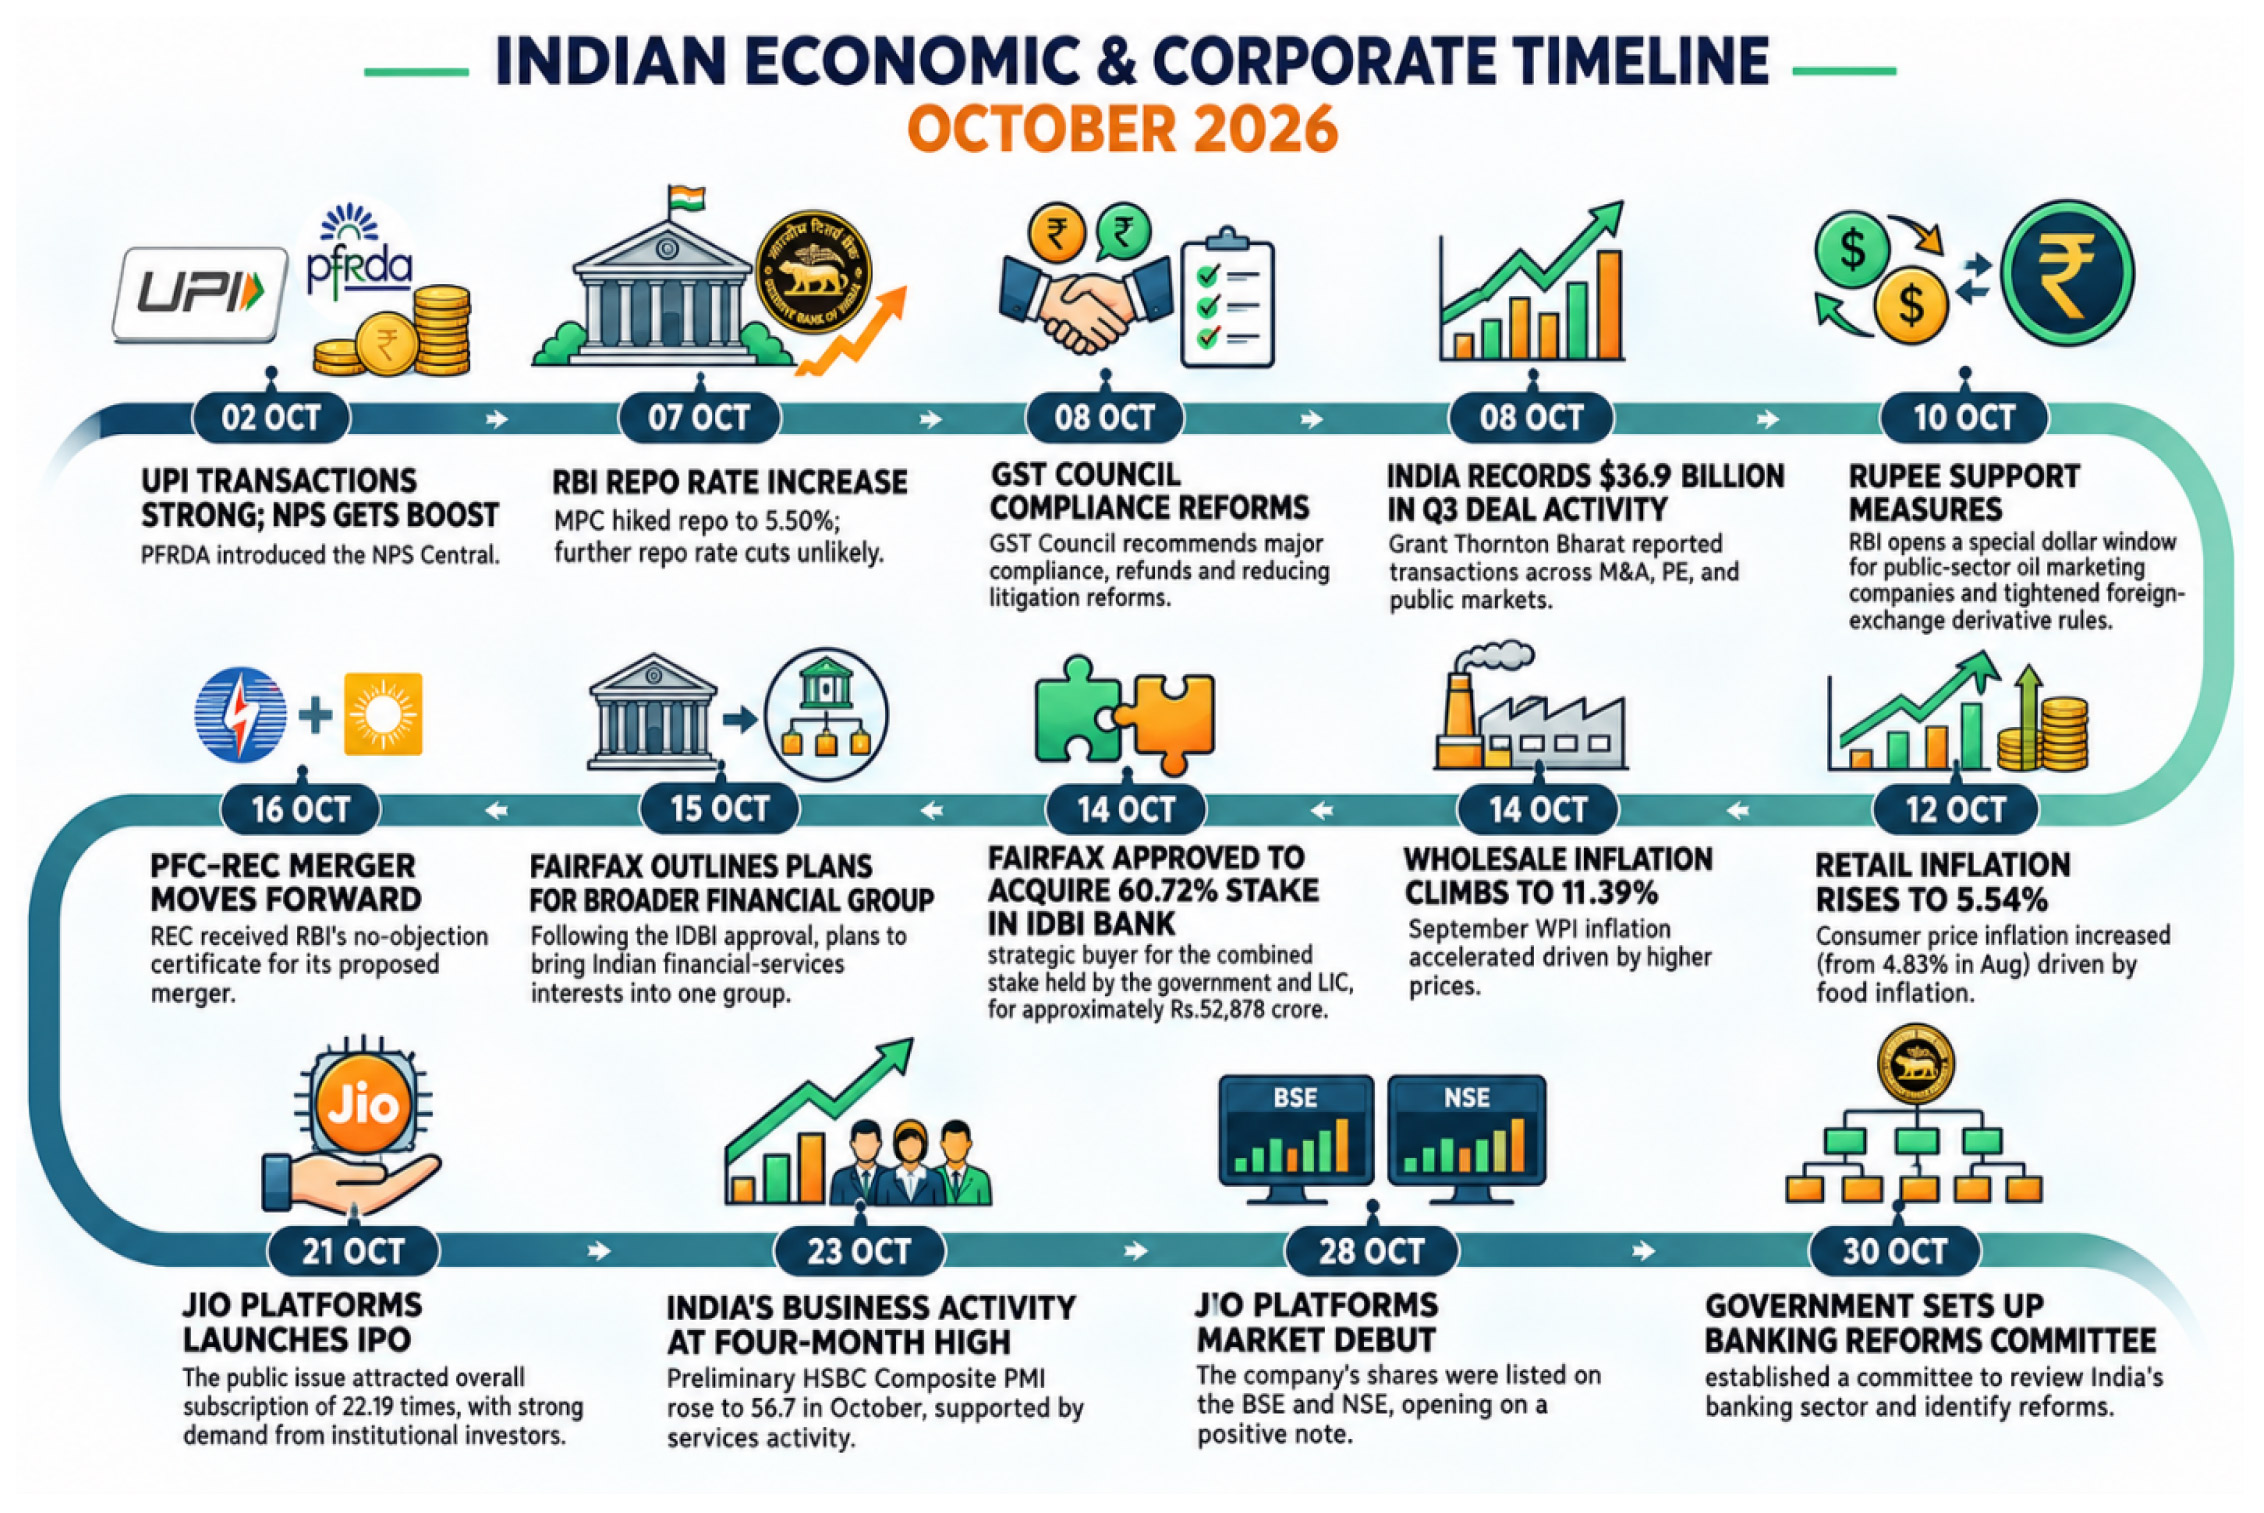
The impact of FII selling was, however, partly absorbed by strong domestic institutional participation. DIIs, including mutual funds, insurance companies and other domestic financial institutions, remained consistent buyers, recording net purchases of ₹62,220 crore in the exchange cash-market data. Their buying was supported by continued domestic investment flows and helped provide liquidity during periods of foreign selling. Interestingly, foreign investor sentiment improved towards the end of October, with FPIs returning as net buyers and infusing approximately ₹6,300 crore during the final week, October 26–30. This reversal, along with improving corporate earnings and domestic buying, contributed to the recovery in benchmark indices. It is worth noting that depository-based FPI flow figures and exchange-based FII cash-market figures differ because they cover different transaction categories and settlement periods. Depository data separately reported net equity outflows of approximately ₹34,843 crore for October. On the domestic front, the Reserve Bank of India's monetary policy decision also influenced investor sentiment. The Monetary Policy Committee raised the repo rate by 25 basis points to 5.50% on October 7, shifting towards a calibrated tightening stance amid inflationary concerns. The rate hike initially weighed on interest-rate-sensitive sectors, particularly banking and other businesses dependent on borrowing costs, as investors assessed its implications for credit growth, consumption and corporate profitability. Nevertheless, the market witnessed a notable turnaround during the latter half of the month, supported by relatively resilient September-quarter corporate earnings and improving investor confidence. The information technology sector emerged as the strongest performer, with the Nifty IT index gaining approximately 17.69%, supported by encouraging quarterly results, growing interest in artificial intelligence-led business opportunities and attractive valuations following earlier corrections. Positive earnings announcements from selected companies also encouraged selective investment in large-cap stocks. Furthermore, expectations of a possible reduction in the long-term capital gains tax rate from 12.5% provided an additional boost to sentiment, although no such policy change had been officially announced. Despite the recovery in benchmark indices, broader market performance remained subdued. The Nifty Midcap 100 and Smallcap 100 declined by
The Indian debt market witnessed broad-based pressure during October 2026, with government securities, Treasury Bills, State Development Loans, corporate bonds and money-market instruments recording an increase in yields and a corresponding decline in bond prices. Unlike periods when long-term and short-term interest rates move in different directions, October saw borrowing costs harden across most segments, reflecting persistent inflationary concerns, rising crude oil prices, tightening banking-system liquidity and the Reserve Bank of India's shift towards a more restrictive monetary policy stance. The benchmark 10-year Government Security (G-Sec) yield increased by approximately 22.5 basis points, rising from around 7.18% at September-end to 7.414% on October 30, while touching nearly 7.49% during the month. The five-year G-Sec yield also increased by approximately 28 basis points by mid-October, indicating a broader repricing of interest-rate expectations. The pressure on government bonds was largely driven by the RBI's 25-basis-point repo rate hike to 5.50% on October 7 and its shift from a neutral stance towards calibrated tightening. The nearly 14% rise in Brent crude prices, which reached an intraday high of approximately US$117.55 per barrel, intensified concerns over imported inflation, the current account deficit and pressure on the rupee. Persistent foreign investor outflows from Indian debt, elevated global bond yields and expectations of further monetary tightening added to the selling pressure. The RBI's liquidity absorption measures, open-market operations and foreign exchange interventions also contributed to tighter domestic liquidity, affecting demand for government securities. The Treasury Bill market experienced a similar upward movement in yields as investors adjusted their return expectations amid tighter liquidity and higher policy rates. By October 28, yields on 91-day, 182-day and 364-day Treasury Bills had increased to approximately 5.93%, 6.55% and 6.69%, respectively, compared with 5.21%, 5.62% and 5.91% at the September 9 auction. The increase was particularly pronounced in the six-month and one-year maturities, reflecting higher short-term funding requirements, reduced banking-system liquidity and expectations of further interest-rate tightening. Investor demand remained cautious, with the RBI rejecting bids at a ₹23,000 crore Treasury Bill auction on October 21, indicating that market participants were seeking higher returns. State Development Loans (SDLs) also witnessed a rise in borrowing costs, with select 10-year state bond yields crossing the 8% mark and reaching approximately 8.03–8.15%. The increase largely followed the upward movement in G-Sec yields, coupled with higher state government borrowing requirements, tighter liquidity and changing demand-supply conditions. The corporate bond market remained under pressure as higher government security yields translated into increased borrowing costs for companies. Ten-year AAA-rated corporate bond yields moved towards 8.18–8.35% during the latter part of October, with public-sector corporate bond yields rising alongside benchmark government securities. Higher financing costs, reduced banking liquidity and inflation uncertainty prompted investors to demand better returns on corporate debt. Nevertheless, highly rated public-sector enterprises continued to access the bond market, with REC raising ₹4,000 crore through five-year bonds at a cut-off yield of 8.30% on October 26. The Commercial Paper (CP) market also experienced a hardening of rates as companies and non-banking financial companies (NBFCs) faced higher short-term funding costs. One-year CP rates for AAA-rated NBFCs reached approximately 8.10%, while shorter-maturity funding rates also moved higher amid reduced surplus liquidity, rising Treasury Bill yields and increased competition for funds. Similarly, the Certificate of Deposit (CD) market witnessed an upward movement in rates as banks increasingly relied on market-based instruments to mobilise funds and meet their funding requirements. One-year CD rates for public-sector banks approached 7.90% during late October, while three-month CD yields rose by approximately 50 basis points to 6.80% by mid-month. Some one-year PSU bank CD rates subsequently crossed 8% in early November, reflecting growing competition among banks to attract deposits and the higher cost of short-term funding. Money-market conditions also tightened considerably, with the weighted average overnight call money rate increasing from approximately 5.21% at September-end to 5.78% on October 23, while the overnight triparty repo rate also moved higher. The banking-system liquidity surplus declined sharply from approximately ₹11.16 lakh crore in September to around ₹542 crore by October 22, reflecting RBI liquidity absorption, foreign exchange interventions, tax-related outflows and increased festive-season currency demand. Overnight Indexed Swap (OIS) rates also hardened, with the one-year OIS rising by approximately 51 basis points to 6.72% and the five-year OIS increasing by around 21 basis points to 6.86%, indicating expectations of a tighter interest-rate environment. Overall, October 2026 proved challenging for the Indian fixed-income market, with rising crude oil prices, inflationary pressures, the RBI's monetary tightening, foreign investor outflows and deteriorating banking-system liquidity contributing to a broad-based increase in yields. The benchmark 10-year G-Sec yield rising to approximately 7.41% reflected the market's cautious outlook, while higher Treasury Bill, SDL, corporate bond, CP and CD rates highlighted the widespread increase in borrowing costs. October was therefore characterised by simultaneous pressure on long-term bond valuations and short-term funding conditions, resulting in declining bond prices, higher financing costs and a more challenging environment for fixed-income investors.
Precious metals delivered a strong performance in
August 2026, with both gold and silver witnessing sharp
rallies and reaching fresh record levels before
experiencing some profit-taking towards the end of the
month. Domestic 24-carat gold started August at around
₹1,43,680 per 10 grams on August 3 and gained steadily
during the month, crossing ₹1,48,000–₹1,49,000 in the
first week before accelerating further. By August 24, gold
reached a fresh record of around ₹1,64,730 per 10 grams,
gaining nearly 15% from the beginning of the month.
Internationally, Comex gold also touched a new high of
around US$4,737 per ounce, highlighting the strength of
the global bullion rally. The sharp rise was supported by a
combination of expectations for a more accommodative
US monetary-policy outlook, lower US yields, dollar
weakness, geopolitical uncertainty and continued
institutional demand. However, the pace of appreciation
left gold vulnerable to profit-booking. By August 31,
domestic gold had corrected to approximately ₹1,55,430
per 10 grams, nearly 5% below its August peak, although
it remained substantially higher than its level at the
beginning of the month.
Silver followed a similar upward trajectory but
demonstrated greater resilience during the late-month
correction. Domestic silver started August at around
₹2,184 per 10 grams, equivalent to approximately ₹218
per gram, and climbed to about ₹2,479 per 10 grams by
August 24. Although it eased towards month-end, silver
declined only modestly to approximately ₹2,423 per 10
grams, or ₹2,42,320 per kilogram, on August 31. This still
represented a monthly gain of more than 11% based on the
domestic prices cited. Internationally, Comex silver traded
around US$67 per ounce towards the end of August. Silver's
relative outperformance during the correction reflected its
additional support from industrial demand and tight
physical inventories. Demand from solar photovoltaic
applications, electric vehicles, electronics and data-centre
infrastructure remained an important structural driver, while
investment demand provided further momentum.
Several factors contributed to the broad-based rally in
precious metals. First, expectations of a softer US Federal
Reserve policy stance and periods of weakness in the US
dollar reduced the opportunity cost of holding non-yielding
assets such as gold and silver. Expectations of lower real
interest rates, reinforced by softer US economic and
employment indicators, encouraged investors to increase
exposure to bullion. US Treasury yields also declined at
various points during the month, providing an additional
tailwind. Second, investment flows improved materially.
After a period of weakness and outflows, global gold
exchange-traded products witnessed renewed buying, with
significant inflows during early and mid-August, signalling a
recovery in institutional investor sentiment. Indian gold ETFs
also continued to attract investor interest, supporting
domestic investment demand.
Central-bank purchases remained another important
structural pillar of the precious-metals market. Countries
including China, Poland, Uzbekistan and Kazakhstan
continued to accumulate gold, reinforcing expectations that
official-sector demand would remain strong. Such
purchases provide a relatively stable source of demand and
have helped strengthen the longer-term investment case for
gold despite periodic corrections. Geopolitical tensions also
supported safe-haven demand. Renewed concerns
surrounding the Middle East, including tensions affecting
regional shipping and energy supplies, encouraged
investors to seek defensive assets. Rising crude-oil prices
added to market uncertainty, although the impact of higher
energy prices on bullion was mixed because persistent
inflation could potentially delay monetary easing.
Silver benefited from the monetary and safe-haven factors
supporting gold while also adding momentum from its
industrial fundamentals. Tight inventories, robust industrial
consumption and expectations of continued demand from
renewable energy, electric vehicles, electronics and
technology infrastructure helped silver outperform during
the rally.
Overall, August 2026 was a particularly strong month for
bullion, driven by a combination of lower real yields,
dollar movements, geopolitical uncertainty, central-bank
accumulation and renewed investment flows. Silver
additionally benefited from structural industrial demand
and supply tightness, enabling it to demonstrate greater
resilience during the late-month correction.
October 1 to approximately ₹1,811 on October 31,
representing a fall of about 18.54%. MCX December
silver futures also witnessed substantial selling,
dropping below ₹2 lakh per kilogram during the month.
Apart from the factors affecting gold, silver was
particularly vulnerable because of its dual role as a
precious metal and an industrial commodity.
Expectations of higher US interest rates, dollar strength
and rising bond yields weakened investor appetite, while
profit-booking and the unwinding of leveraged positions
intensified the sell-off. Concerns over industrial
consumption, particularly in solar panels, electronics and
electric vehicles, further affected sentiment. Slower
manufacturing activity and the reduced use of silver in
solar-panel production also raised concerns about future
demand.
In India, silver prices followed the global downward trend,
with additional pressure from changing domestic supply
conditions and subdued investment demand.
Government approval for approximately 6,500 tonnes of
silver imports over the following six months eased earlier
concerns about shortages and reduced domestic
premiums. The increase in import duty from 6% to 15% in
May 2026 kept landed costs elevated but could not
prevent the price correction. Despite the festive season,
consumers remained cautious amid sharp price
fluctuations and expectations of further declines.
Jewellery demand held up relatively better than
purchases of coins and bars. Currency movements and
India's dependence on imported silver also influenced
domestic prices.
Overall, October marked a broad correction in precious
metals, driven primarily by changing global monetary
expectations, dollar strength and investor liquidation.
Gold was affected mainly by rising yields and
profit-booking, while silver faced additional pressure
from industrial-demand concerns and easing domestic
supply constraints. Although the correction was
significant, continued geopolitical uncertainty and
central-bank demand remained important longer-term
supports for gold, while silver's outlook continued to
depend on both investment sentiment and industrial
consumption
October 2026 witnessed a notable recovery in the Indian rupee, which appreciated approximately 1% against the US dollar to close around ₹94.93–95.00, marking its strongest monthly performance since February. The currency began the month under considerable pressure, approaching record-low levels amid elevated crude oil prices, foreign portfolio investor (FPI) outflows and geopolitical uncertainty. However, it staged a sharp recovery during the middle of the month, gaining nearly 2% in the week leading up to October 16, its strongest weekly advance in seven months. The improvement was largely driven by measures introduced by the Reserve Bank of India (RBI) to curb speculative dollar demand and ease pressure in the foreign exchange market. These included redirecting dollar purchases by oil marketing companies away from the spot market, providing foreign currency directly to public-sector oil companies, tightening banks' foreign exchange positions and restricting certain forward-contract transactions. These steps reduced immediate demand for dollars and encouraged offshore traders to unwind bearish positions against the rupee. Corporate forward dollar purchases also declined during the month, further easing pressure on the domestic currency. A softer US dollar and declining US Treasury yields towards the latter part of October provided additional support by improving sentiment towards emerging-market currencies. The RBI's 25-basis-point policy rate hike to 5.5%, its first increase in nearly four years, also supported the rupee by improving the relative attractiveness of domestic assets and signalling the central bank's commitment to maintaining currency stability. Expectations of improved capital inflows and measures to mobilise foreign currency deposits further strengthened sentiment. Nevertheless, the recovery remained vulnerable to external pressures. Brent crude prices rose sharply during October amid geopolitical tensions and supply-disruption concerns in West Asia, increasing India's import bill and demand for dollars. Given that India imports nearly 90% of its crude oil requirements, higher oil prices place pressure on the trade balance and current account deficit, while also increasing the cost of imported energy. Persistent FPI outflows from Indian equities and debt markets added to the pressure, as overseas investors selling domestic assets converted their rupee proceeds into dollars. Importers also maintained substantial dollar purchases to meet payment obligations and hedge against further currency fluctuations, keeping underlying demand for foreign exchange elevated. Global risk aversion, geopolitical uncertainty and changing expectations regarding US monetary policy continued to influence currency movements. Towards the end of October, the rupee briefly weakened as crude approached US$115 per barrel and importer demand for dollars increased, before recovering to approximately ₹94.93 per dollar on October 30. The movement reflected the significant influence of RBI intervention and currency-market regulations in stabilising the exchange rate, rather than a complete improvement in India's external-sector fundamentals. Across Asia, currency performance was mixed during the month. The Chinese yuan and South Korean won strengthened, supported by export earnings and foreign currency inflows, while the Vietnamese dong benefited from tighter domestic liquidity, trade surpluses and steady foreign investment. The Japanese yen remained broadly stable, whereas the Philippine peso and Indonesian rupiah faced pressure from portfolio outflows, domestic economic concerns and country-specific risks. The Indian rupee's recovery was relatively strong compared with several regional currencies, highlighting the impact of active central-bank intervention. Overall, October 2026 marked a policy-supported recovery for the Indian rupee, with RBI measures, reduced speculative dollar demand and a softer US dollar helping it regain ground. However, elevated crude oil prices, persistent foreign investor outflows and India's dependence on imported energy continued to pose challenges. Consequently, the currency remained sensitive to movements in global oil prices, capital flows and international monetary policy, suggesting that sustained stability would depend on both continued RBI support and an improvement in external economic conditions.
October 2026 witnessed a sharp rally in crude oil prices, extending the upward trend for the fourth consecutive month, with Brent and West Texas Intermediate (WTI) gaining approximately 13.6% and 15.2%, respectively. Brent crude settled at USD 117.64 per barrel, while WTI closed around USD104 per barrel on October 30, with both benchmarks reaching their highest levels since late April. The rally was primarily driven by escalating geopolitical tensions in the Middle East, fears of supply disruptions and rising transportation costs. Renewed concerns over the US-Iran conflict, attacks on Saudi oil infrastructure and incidents involving commercial vessels in the Strait of Hormuz heightened uncertainty over the uninterrupted movement of crude supplies. The Strait of Hormuz is particularly significant as it handles nearly one-fifth of global energy shipments, making any threat to its security a major concern for international oil markets. Attacks on tankers and regional energy infrastructure, including Saudi facilities and pipeline networks, increased the risk premium embedded in crude prices. Shipping disruptions, higher marine insurance premiums and limited tanker availability further raised transportation costs, with freight expenses reportedly reaching significantly above normal levels. Supply concerns were also aggravated by temporary disruptions to US offshore oil production ahead of Hurricane Isaias, which reportedly affected approximately 1.3 million barrels per day of output, while a pipeline-related disruption in Libya added to supply uncertainty. The market remained volatile throughout the month, with prices briefly easing on hopes of diplomatic progress and improved Gulf exports before recovering following renewed security concerns. Despite the geopolitical risks, the rally was partly moderated by recovering crude exports from Gulf producers, alternative export routes through Saudi Arabia and the UAE, and expectations of softer global demand amid higher interest rates. Nevertheless, the physical market remained tight, with elevated near-term crude prices reflecting concerns over immediate supply availability. In India, the increase in international crude prices translated into higher procurement costs, given the country's dependence on imported energy. The Indian crude oil basket averaged approximately USD 121.85 per barrel in October, compared with USD 116.09 in September, representing an increase of around 5%. Since India imports nearly 90% of its crude oil requirements, the price rise significantly increased the country's import expenditure and added pressure to the trade balance and current account. The depreciation of the rupee against the US dollar further increased the cost of imports, as international crude purchases are largely dollar-denominated. In addition, higher freight, shipping and insurance expenses raised the landed cost of crude for domestic refiners, particularly those sourcing supplies from the Middle East. Indian refiners also increased procurement to maintain adequate inventories and support refinery operations, with crude imports reportedly averaging around 5.6 million barrels per day during the month. However, elevated input costs created pressure on oil marketing companies (OMCs), as relatively stable retail petrol and diesel prices limited their ability to pass on the full increase in procurement expenses to consumers. This raised concerns over marketing margins, profitability and the potential fiscal implications of prolonged high oil prices. The increase also heightened inflationary risks, as higher energy and transportation costs could gradually feed into the prices of goods and services. Overall, October 2026 was marked by a geopolitically driven crude oil rally, in which concerns over supply security, shipping disruptions and infrastructure attacks outweighed the moderating influence of recovering exports and demand uncertainties. For India, the rise was particularly challenging because of its dependence on imported crude, currency weakness and elevated transportation costs. Consequently, sustained high oil prices remained a key risk to domestic inflation, the rupee, the country's external balances and the financial performance of oil marketing companies.
The headline story for Indian mutual funds in October
2026 was resilient retail SIP-led inflows amid market
volatility and a slowdown in discretionary equity buying.
The industry’s quarterly average AUM rose to ₹89.51 lakh
crore in Q2 FY27, while October equity deployment
moderated and debt funds continued to see outflows.
India’s mutual fund industry witnessed moderating equity
investments in October, with net equity purchases falling
to ₹43,024 crore, a three-month low, although cumulative
deployment in 2026 reached ₹4.7 trillion. Retail
participation remained resilient, supported by record
September SIP contributions of ₹32,490 crore and 10.89
crore SIP accounts. Quarterly average AUM rose 4.9%
sequentially and 14.1% year-on-year to ₹89.51 lakh crore
in Q2 FY27. Market volatility, a global technology-led
sell-off, a stronger US dollar and higher interest-rate
expectations encouraged investors to adopt a cautious
approach towards equities, particularly mid-cap and hybrid
funds. Debt funds faced seasonal redemptions of ₹1.83 lakh
crore in September, driven by treasury and corporate
liquidity requirements. However, corporate bond funds
attracted ₹15,051 crore in October, their highest inflow in 19
months. Gold ETFs also gained traction, with AUM reaching
₹1.91 lakh crore, while Carnelian’s maiden small-cap NFO
mobilised ₹632 crore. Overall, investors increasingly
favoured selective equity exposure, corporate bonds and
gold amid market uncertainty.
INSURANCE: WRAP
India’s insurance sector witnessed significant regulatory
developments in October 2026, led by IRDAI’s proposed
overhaul of insurance distribution economics. The regulator
considered reintroducing product- and channel-specific
commission caps, alongside lower
expense-of-management limits, drawing concerns from
brokers and NBFCs over potential revenue losses. IRDAI
also expanded insurers’ investment options to include
private companies, infrastructure SPV debt and
securities-lending transactions, subject to safeguards. In
health insurance, the regulator upgraded its Business
Analytics Platform to streamline regulatory reporting and
product administration, while strong demand supported
a 46% year-on-year rise in new health premiums. IRDAI
also cautioned against higher customer co-payments and
dynamic pricing practices. Following flood-related
disruptions, insurers were directed to expedite claims,
deploy surveyors and establish dedicated assistance
facilities. Additionally, the regulator emphasised curbing
mis-selling through incentives linked to policy persistence
rather than initial sales. Ather Energy’s subsidiary also
received registration as a composite corporate insurance
agent, enabling distribution across life, general and health
insurance.