Topic 4: RUPEE: FESTIVE LIGHTS
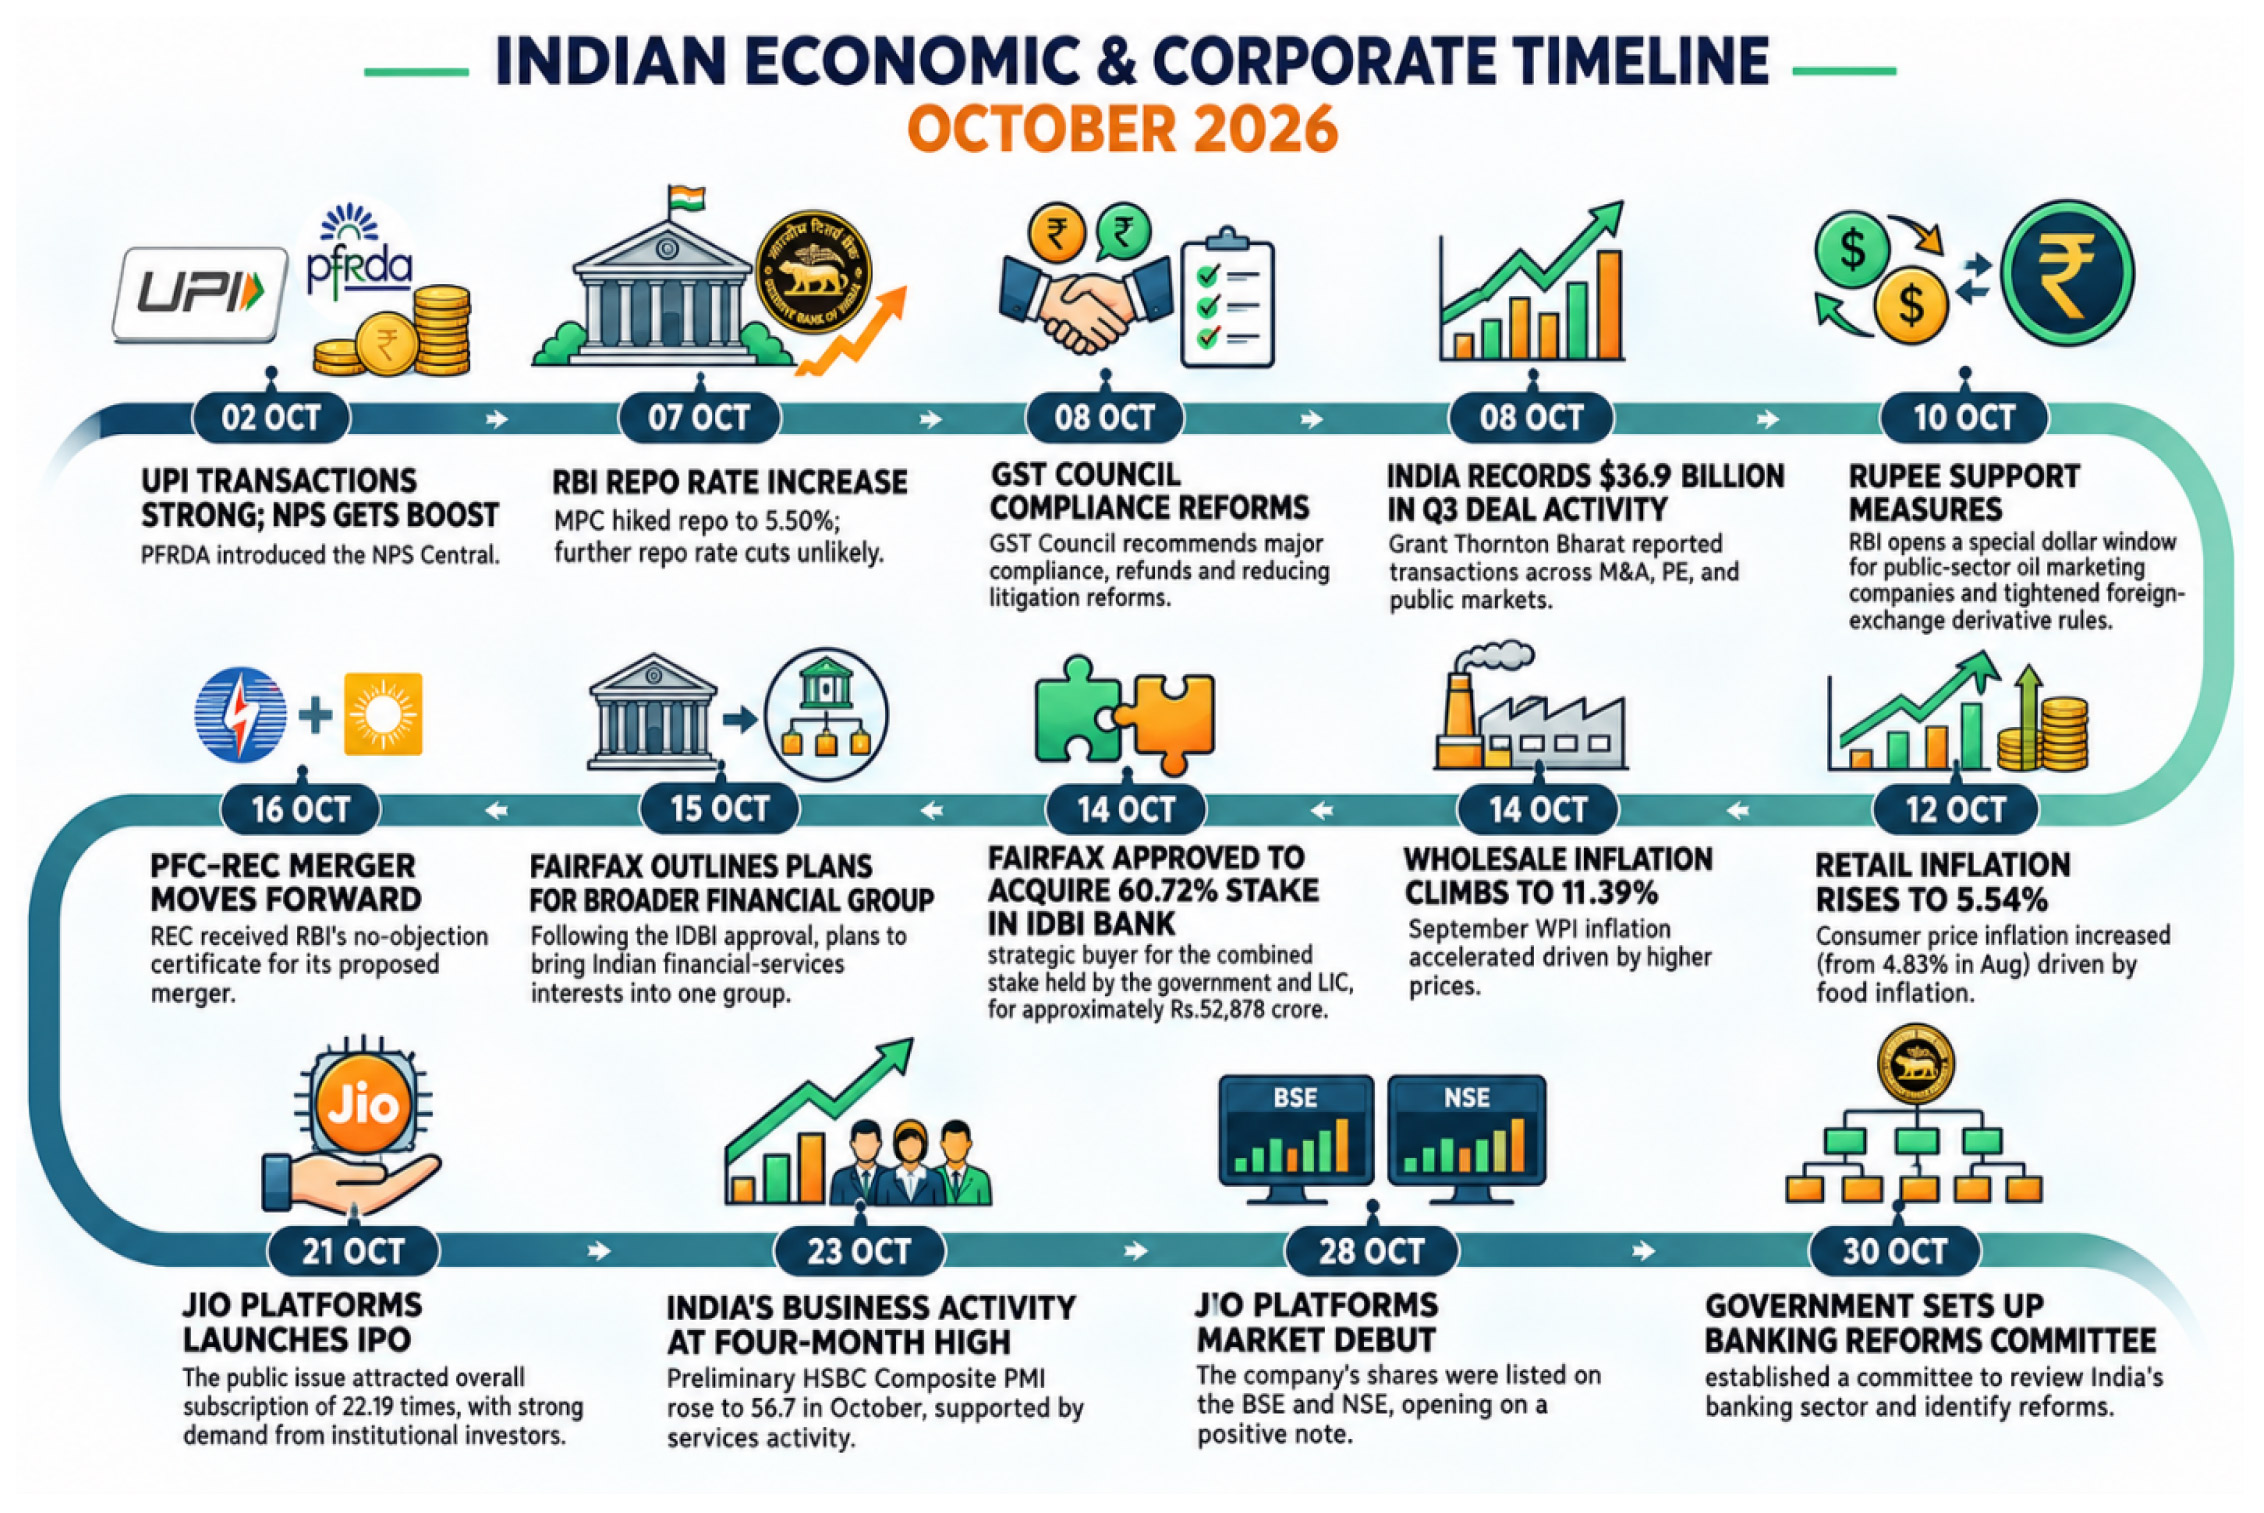
October 2026 witnessed a notable recovery in the Indian rupee, which appreciated approximately 1% against the US dollar to close around ₹94.93–95.00, marking its strongest monthly performance since February. The currency began the month under considerable pressure, approaching record-low levels amid elevated crude oil prices, foreign portfolio investor (FPI) outflows and geopolitical uncertainty. However, it staged a sharp recovery during the middle of the month, gaining nearly 2% in the week leading up to October 16, its strongest weekly advance in seven months. The improvement was largely driven by measures introduced by the Reserve Bank of India (RBI) to curb speculative dollar demand and ease pressure in the foreign exchange market. These included redirecting dollar purchases by oil marketing companies away from the spot market, providing foreign currency directly to public-sector oil companies, tightening banks' foreign exchange positions and restricting certain forward-contract transactions. These steps reduced immediate demand for dollars and encouraged offshore traders to unwind bearish positions against the rupee. Corporate forward dollar purchases also declined during the month, further easing pressure on the domestic currency. A softer US dollar and declining US Treasury yields towards the latter part of October provided additional support by improving sentiment towards emerging-market currencies. The RBI's 25-basis-point policy rate hike to 5.5%, its first increase in nearly four years, also supported the rupee by improving the relative attractiveness of domestic assets and signalling the central bank's commitment to maintaining currency stability. Expectations of improved capital inflows and measures to mobilise foreign currency deposits further strengthened sentiment. Nevertheless, the recovery remained vulnerable to external pressures. Brent crude prices rose sharply during October amid geopolitical tensions and supply-disruption concerns in West Asia, increasing India's import bill and demand for dollars. Given that India imports nearly 90% of its crude oil requirements, higher oil prices place pressure on the trade balance and current account deficit, while also increasing the cost of imported energy. Persistent FPI outflows from Indian equities and debt markets added to the pressure, as overseas investors selling domestic assets converted their rupee proceeds into dollars. Importers also maintained substantial dollar purchases to meet payment obligations and hedge against further currency fluctuations, keeping underlying demand for foreign exchange elevated. Global risk aversion, geopolitical uncertainty and changing expectations regarding US monetary policy continued to influence currency movements. Towards the end of October, the rupee briefly weakened as crude approached US$115 per barrel and importer demand for dollars increased, before recovering to approximately ₹94.93 per dollar on October 30. The movement reflected the significant influence of RBI intervention and currency-market regulations in stabilising the exchange rate, rather than a complete improvement in India's external-sector fundamentals. Across Asia, currency performance was mixed during the month. The Chinese yuan and South Korean won strengthened, supported by export earnings and foreign currency inflows, while the Vietnamese dong benefited from tighter domestic liquidity, trade surpluses and steady foreign investment. The Japanese yen remained broadly stable, whereas the Philippine peso and Indonesian rupiah faced pressure from portfolio outflows, domestic economic concerns and country-specific risks. The Indian rupee's recovery was relatively strong compared with several regional currencies, highlighting the impact of active central-bank intervention. Overall, October 2026 marked a policy-supported recovery for the Indian rupee, with RBI measures, reduced speculative dollar demand and a softer US dollar helping it regain ground. However, elevated crude oil prices, persistent foreign investor outflows and India's dependence on imported energy continued to pose challenges. Consequently, the currency remained sensitive to movements in global oil prices, capital flows and international monetary policy, suggesting that sustained stability would depend on both continued RBI support and an improvement in external economic conditions.